

Does Homeowners Insurance Cover Tree Removal in Georgia?
Quick answer: usually only when a tree is brought down by a covered event — wind, hail, the weight of ice or snow, lightning — and it lands on your house or another insured structure, or blocks your driveway. Getting the tree off the house is normally paid as part of the house repair. Hauling the wood away from your property is a separate, small allowance: on the standard policy form, $500 per tree and $1,000 per storm. A tree that falls in the open yard, or a dead tree you want taken down before it falls, is on you.
- Covered: a storm-felled tree on your home, garage, shed or fence — whoever owned the tree.
- Covered, smaller: a fallen tree blocking your driveway or a wheelchair ramp, even with no damage.
- Capped: removing the wood from your property — typically $500 a tree, $1,000 a storm, after your deductible.
- Not covered: preventive removal, dead or rotting trees, and trees that fall in open yard without hitting anything.
- Georgia, 2026: insurers that cancel or non-renew over aerial photos — overhanging trees included — must now show you the images.
This is the call we take most after a North Georgia storm: a tree is on the house, the family is safe, and the next question is whether insurance pays for the tree. The honest answer is that it depends on three things — what knocked the tree down, what it landed on, and which part of the job you are asking about.
Below is what the standard homeowners policy says in its own words, the cases that are and are not covered, and how to keep a claim clean. We are a tree service, not an insurance agent: your declarations page and your adjuster have the final word on your policy.
What does a standard homeowners policy say about trees?
Most homeowners policies in Georgia are built on the same industry form, the ISO HO-3 "special form" (the sample policy is published by the Insurance Information Institute). It handles trees in three separate places, and mixing them up is where most of the confusion starts:
- Damage to your house. When a tree falls on the house in a windstorm, the house damage is a normal dwelling claim — the same as any other covered loss. Getting the tree off the roof so the roof can be repaired is part of that repair.
- Tree debris removal. A separate "additional coverage" pays "up to $1,000" to remove trees from your property when they were felled by windstorm, hail, or the weight of ice, snow or sleet — but only if they damaged a covered structure, or blocked a driveway or a ramp for a disabled person. "No more than $500" of that is paid for any one tree.
- The trees themselves. Your trees, shrubs and plants are covered for a short list of causes — fire or lightning, explosion, riot, aircraft, a vehicle you do not own, vandalism and theft — up to 5% of your dwelling limit, and no more than $500 for any one tree. Wind is not on that list.
Insurers can and do change this wording, and many sell endorsements that raise the tree limits. But if you have never looked, the numbers above are the place to start.
When does insurance pay to remove a fallen tree?
Put the policy wording against the situations we actually see, and the pattern is clear:
| What happened | House repair | Tree removal |
|---|---|---|
| Storm drops a tree on the house, garage or shed | Covered | Off the house: part of the repair. Away from the property: capped ($500/tree) |
| Storm drops a tree on your fence | Covered (other structures) | Capped ($500/tree) |
| Storm drops a tree across the driveway, nothing damaged | Nothing to repair | Usually covered, capped |
| Storm drops a tree in the open yard | Nothing to repair | Usually not covered |
| Lightning strikes a tree and it falls in the yard | Nothing to repair | Check your policy — lightning damage to trees is a covered cause |
| A dead or rotting tree falls on the house | Often disputed | Often disputed |
| You remove a dead, leaning or risky tree before it falls | n/a | Not covered |
| A flood or earthquake brings the tree down | Not covered without a separate policy | Not covered |
Three comparison guides we checked — Policygenius, Insurify and Triple-I — agree on the same core cases. Where they differ is on lightning: some say it is covered even when the tree hits nothing, others do not mention it. That is a sign to read your own policy rather than trust a general rule.
Is the $500-per-tree limit the most insurance will pay?
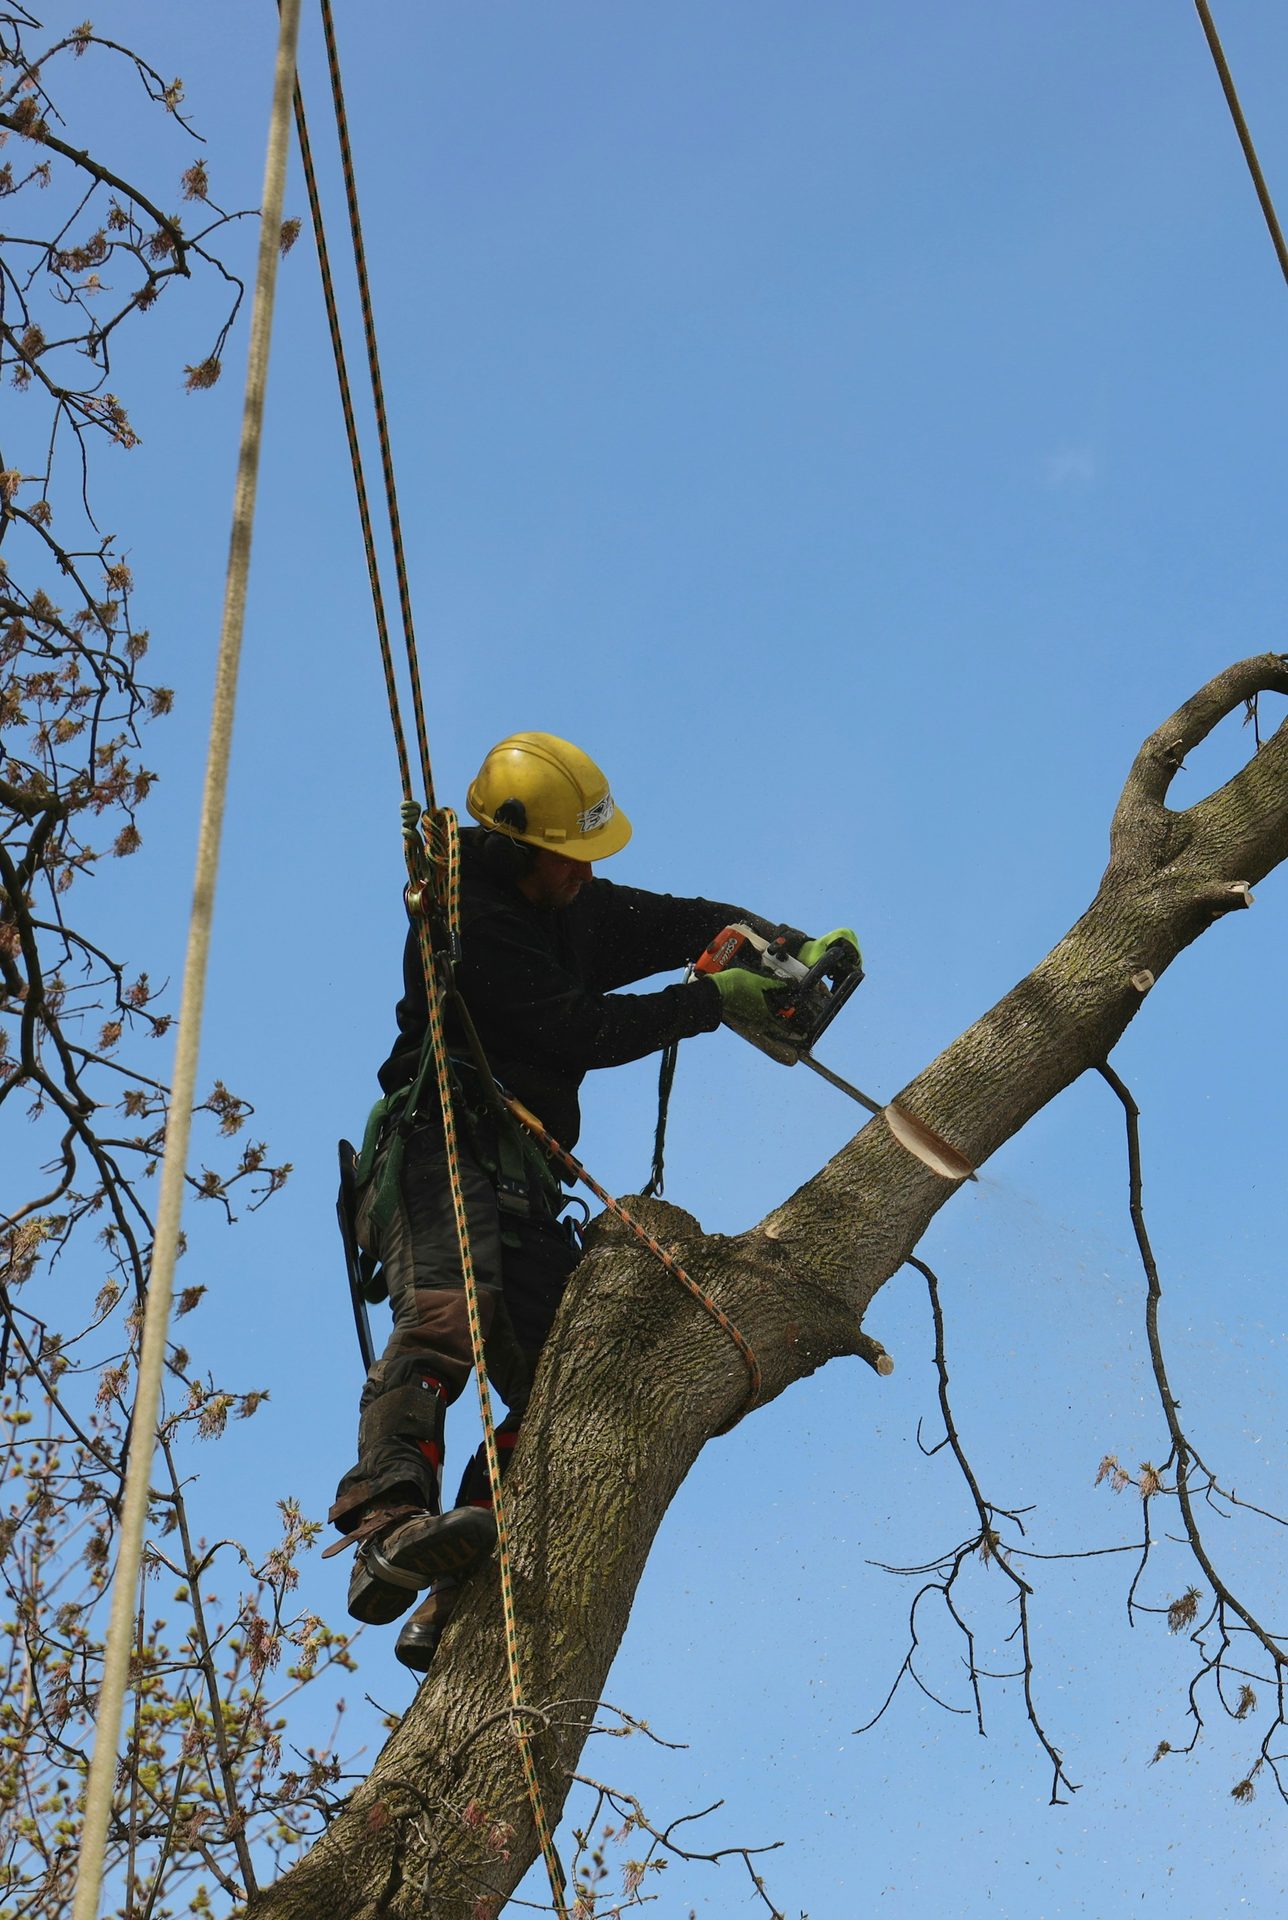
No — and this is the most expensive misunderstanding in tree claims. The $500-per-tree, $1,000-per-storm limit applies to removing the tree from your property. It does not cap the work of getting the tree off your house.
The Florida Association of Insurance Agents puts it bluntly in its debris removal primer, written from the same standard policy: there is no internal limit to get a tree off the house, because that is part of the cost of repairing the house, and "some adjusters will incorrectly say there is a $500 limit to remove tree from house."
That matters because the hard part of a tree-on-house job is the lift: rigging or a crane to take the weight off the roof without making the damage worse. Hauling the wood away afterward is the small part. For reference, Policygenius, citing HomeAdvisor, puts an ordinary tree removal at about $750 on average with a typical range of $200 to $2,000 — and a tree on a roof is not an ordinary removal. A $500 haul-away allowance was never meant to pay for that.
What tree removal does insurance never cover?
- Preventive removal. A tree leaning toward the house, or a big limb over the bedroom, is maintenance until something falls. The policy covers sudden loss, not risk.
- Dead, diseased or rotting trees. If a tree was visibly dead and comes down, the insurer may argue the loss came from neglect, not the storm. Triple-I is direct about it: poor maintenance is not covered.
- Trees that fall and hit nothing. Wind-felled trees in open yard are generally yours to clean up, unless they block the driveway.
- Flood and earthquake. Standard policies exclude both, and the trees that come down with them.
- Replacing the tree. The standard tree coverage does not include wind, so a storm-killed shade tree is not replaced.
The practical lesson for Georgia homeowners is in the second bullet. Our soils are clay, our storms come with saturated ground, and our big water oaks, pines and tulip poplars carry a lot of weight high up. The tree that is cheapest to deal with is the dead one before the storm, not after — these are the warning signs we look for.
Whose insurance pays when a neighbor's tree falls on your house?
Yours, in the first instance. The policy covers your house when a tree hits it, no matter whose yard the tree grew in, and you claim on your own policy.
Where it gets interesting is afterward. If the tree was healthy and a storm brought it down, it is usually treated as nobody's fault. If the tree was dead or rotting and your neighbor had reason to know, your insurer may try to recover what it paid from your neighbor's insurer — a process called subrogation — and if it succeeds you may get your deductible back. Our post on neighbor trees goes through how that plays out in Georgia, and who is responsible under Georgia law when the tree was on the line.
What if the tree falls on your car?
The car is an auto claim, not a home claim: damage from a falling tree falls under the comprehensive part of an auto policy. Your homeowners policy may still pay to remove the tree if it is blocking the driveway. What to do when a branch lands on your car has the step-by-step.
How do you keep a tree claim from being denied?
Most denied or short-paid tree claims we see come down to missing evidence, not missing coverage. In order:
- Get everyone out and away from the tree. If anyone is hurt, lines are down, or you smell gas, call 911 first. Never go near a downed power line.
- Photograph before anything is cut. The tree, where it came from, the root plate or break, the damage, and the whole house from each side. Video is better.
- Call your insurer or agent promptly. The policy requires prompt notice.
- Stop the damage getting worse. The policy expects you to make reasonable, necessary repairs to protect the house — a tarp, or taking the weight off the roof — and it pays the reasonable cost of doing so. Keep every receipt. You do not have to wait days for an adjuster while rain comes through the roof.
- Get an itemized written estimate that separates removing the tree from the structure, hauling it from the property, and any emergency tarping.
- Keep the wood until the adjuster says otherwise if there is any question about rot or cause. A cut log shows whether the tree was sound.
Documenting tree damage for an insurance claim covers the photo list in detail. If a tree is on your house right now, start here instead — or call our 24/7 emergency crew on (678) 482-9994.
Can your insurer make you remove a tree in Georgia?
Increasingly, insurers look at your roof and yard from the air before they renew you, and overhanging limbs are one of the things they flag. A notice telling you to trim or remove a tree is not a claim — it is underwriting, and the cost is yours.
Georgia changed the rules in 2026. Under House Bill 1344, signed by Governor Kemp in May 2026, an insurer that cancels or refuses to renew an owner-occupied home policy based on aerial or satellite images has to provide the images, or tell you how to see them, with the notice, and there is an appeal process to correct errors, according to the insurance-industry bulletin AAIS. The same law gives policyholders at least two years to file property claims, according to the Georgia House press office.
If you get a tree notice, do not assume the answer is removal. Ask which tree and what the concern is; often it is one overhanging limb, and clearance trimming solves it for far less than taking the tree down. If you think an insurer is handling your claim or notice unfairly, the Georgia Office of Insurance and Safety Fire Commissioner takes consumer complaints at 1-800-656-2298.
How R & R Tree Service handles insured tree jobs
We have been taking trees off North Georgia houses since 1987, with our own crew and our own crane — never a subcontractor. On an insured job we document the damage for your insurer, take the weight off the roof first so the damage does not spread, and give you a written, itemized estimate in a form adjusters accept. We are licensed and carry general liability and workers' compensation insurance, which is the first thing an adjuster will ask about anyone working on your house.
What we will not do is tell you what your policy covers. We will tell you exactly what the job involves, so you and your adjuster can sort out who pays for which part. Estimates are free: (678) 482-9994.
Frequently asked questions
Does homeowners insurance cover tree removal if the tree did not hit anything?
Usually not. A wind-felled tree in open yard is generally the homeowner's to remove. The exceptions on the standard policy are a tree that blocks your driveway or a wheelchair ramp, and some policies pay when lightning or fire caused the loss.
How much will insurance pay to remove a tree?
On the standard policy form, up to $500 per tree and $1,000 per storm to remove felled trees from your property, after your deductible. Getting a tree off your house is normally paid as part of the house repair, not under that cap.
Will insurance pay to remove a dead tree before it falls?
No. Removing a dead, diseased or leaning tree before it causes damage is maintenance. And if a visibly dead tree falls, the insurer may dispute the claim on the grounds that the loss came from neglect.
My neighbor's tree fell on my house. Who do I call?
Your own insurer. Your policy covers your house regardless of where the tree grew. If the tree was dead and your neighbor knew it, your insurer may try to recover its payment from the neighbor's insurer, and you may get your deductible back.
Can I hire a tree service before the adjuster comes?
Yes, to prevent further damage. The policy expects you to take reasonable steps to protect the house and pays the reasonable cost of them. Photograph everything first, keep receipts, and get an itemized estimate.
Does R & R Tree Service work with insurance companies?
Yes. We document the damage before cutting, provide itemized written estimates adjusters accept, and can talk with your adjuster when asked. Call (678) 482-9994, 24/7 for emergencies.
- Insurance Information Institute — sample ISO Homeowners 3 policy (HO 00 03 10 00): Debris Removal, Reasonable Repairs, Trees, Shrubs and Other Plants, Duties After Loss
- Triple-I — If a tree falls on your house, are you covered?
- Florida Association of Insurance Agents — Debris Removal Primer
- Policygenius — Does homeowners insurance cover tree removal?
- AAIS — Georgia enacts House Bill 1344 (aerial imagery, claims handling)
- Georgia House of Representatives press office — HB 1344 signed
 Call (678) 482-9994